Finance
U.S. Stock Exchanges Seen Reporting Strong Q2 Earnings Amid Volatility-Driven Trading Surge
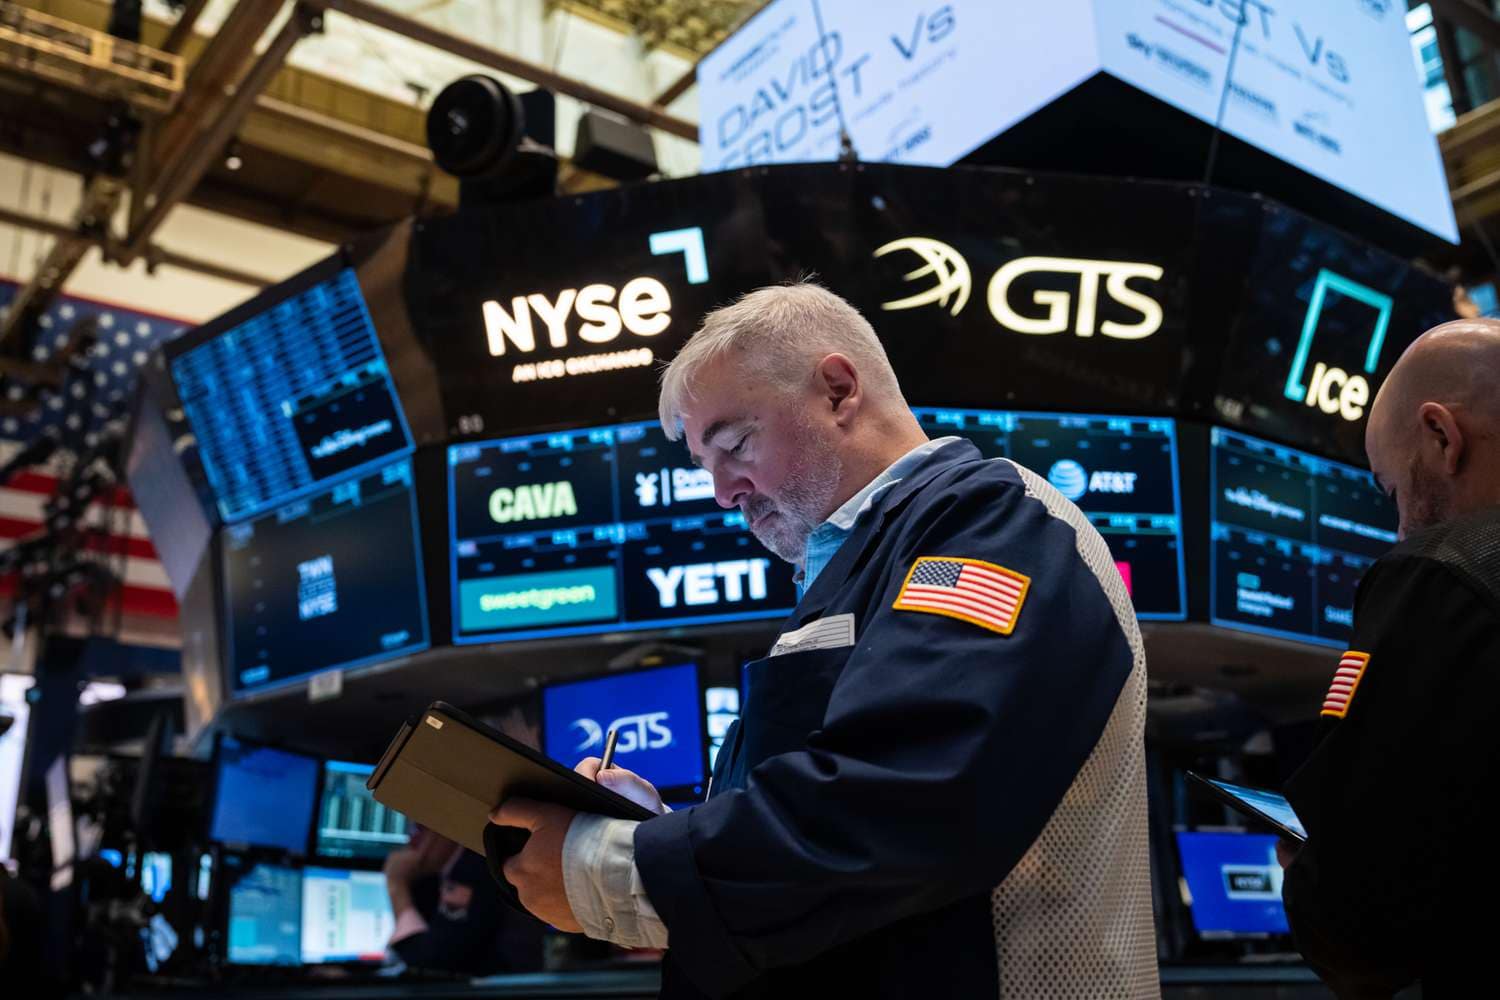
Second-quarter earnings for major U.S. stock exchanges were expected to reflect a notable increase, largely attributed to elevated trading volumes driven by market turbulence surrounding tariff disputes and geopolitical tensions. The surge in activity had reportedly enabled exchanges to collect higher transaction and clearing fees, which typically translate into improved financial results during periods of heightened volatility.
It had been observed that investors, reacting to the evolving macroeconomic landscape and U.S. President Donald Trump’s implementation of sweeping tariff measures, had undertaken widespread repositioning of their investment portfolios. The resulting volatility, further intensified by uncertainties stemming from the Middle East, was said to have created an environment conducive to increased trading across multiple asset classes. Analysts from RBC had commented that the persistence of macroeconomic ambiguity throughout the quarter had supported consistently strong performance in average daily volumes.
Major exchanges, including CME Group, Intercontinental Exchange (ICE), Cboe Global Markets, and Nasdaq, were all reported to have benefited from this spike in market activity. CME Group was said to have recorded a 16% jump in average daily volume (ADV), reaching a new quarterly high of 30.2 million contracts. Similarly, Intercontinental Exchange, which owns the New York Stock Exchange, had experienced a 26% rise in ADV, touching a record 10 million contracts. Trading activity at Cboe Global Markets had also set new benchmarks, with S\&P 500 index options reaching 3.7 million contracts in quarterly ADV, marking an all-time high. Nasdaq, for its part, had seen solid performance in U.S. equities and options trading.
The elevated trading levels were not confined solely to institutional activity. According to insights from brokerage firm Morgan Stanley, retail investor participation had remained resilient throughout the quarter. Retail traders were reported to have continued employing a “buy-the-dip” strategy, even as markets oscillated in response to the tariff disputes and subsequent rebounds in risk assets. This dynamic had provided further tailwinds for the exchanges.
In addition to traditional financial instruments, several exchanges had reportedly expanded their involvement in cryptocurrency markets. CME, for instance, had observed a 136% surge in cryptocurrency ADV during the quarter, driven in large part by unprecedented growth in ether futures. This trend had underscored the increasing integration of digital assets within the mainstream financial system, with more exchanges offering crypto-linked products to meet growing demand.
Although trading volumes had surged during the second quarter, projections for the remainder of the year suggested that activity might moderate slightly, particularly if current sources of uncertainty were resolved. Nonetheless, analysts had indicated that ongoing debates over the extent and timing of future interest rate cuts were expected to maintain volatility in fixed-income markets. Rates trading, therefore, was anticipated to remain active.
Market sentiment had also been lifted by signs of recovery in capital markets. It had been noted that initial public offering (IPO) activity, which had come to a standstill in the first half of the quarter due to volatility, began to pick up as optimism returned. Progress in trade negotiations was believed to have played a role in reigniting investor interest. Companies such as digital bank Chime and stablecoin issuer Circle were said to have gone public in June, reflecting a return of confidence among issuers and investors.
Data from Dealogic had indicated that the total deal value of U.S.-listed IPOs on the Nasdaq nearly tripled to \$13.2 billion in the second quarter, compared to the same period a year earlier. Moreover, the number of new listings had almost doubled, further signaling a revived IPO landscape.
The second-quarter earnings season for U.S. exchanges was scheduled to commence with CME Group reporting results on Wednesday, followed by Nasdaq on Thursday. Cboe and Intercontinental Exchange were expected to release their financial results the following week.
In terms of stock performance, shares of these exchanges had significantly outpaced the broader market. During the first six months of the year, CME and Cboe had each registered gains of nearly 19%, while Intercontinental Exchange and Nasdaq had risen by 23% and 16% respectively. In contrast, the benchmark S\&P 500 index had recorded a comparatively modest increase of 5.5% during the same period.
In conclusion, the strong second-quarter performance expected from U.S. stock exchanges had been shaped by a confluence of market volatility, retail resilience, crypto expansion, and a rebound in IPO activity. While future trading levels may normalize as volatility diminishes, structural shifts in investor behavior and asset diversification were seen as factors that could continue to bolster exchange earnings in the long term.


Finance
Japan Has No Decision on How to Finance Higher Defence Spending
Japan has not yet determined how it will finance a possible increase in defence expenditure, Finance Minister Satsuki Katayama said on Tuesday, October 20, 2026, as the government evaluates its future security requirements and the resources needed to meet them. Her remarks came amid reports that a higher corporate tax could be considered as one option for supporting the country’s planned military spending expansion.
Speaking at a regular news conference in Tokyo, Katayama said the government had not settled on any particular funding mechanism. She explained that officials were still examining the defence capabilities Japan would need and calculating the appropriate level of expenditure required to develop them.
The finance minister’s comments indicate that decisions on financing remain open as the government works through the broader questions surrounding its defence strategy.
Kyodo News reported on Saturday that an additional increase in corporate taxation had emerged within the government as a potential way to pay for a planned expansion of the defence budget. The report, which cited several government sources, also suggested that Japan’s annual defence expenditure under its forthcoming five-year strategy could rise beyond 10 trillion yen.
That projected amount would represent an increase from the approximately 9 trillion yen allocated for the current fiscal year. If annual spending exceeds 10 trillion yen, the government will need to determine how to finance the additional requirements while establishing its priorities for national security.
The difference between the current allocation and the reported future spending level highlights the scale of the potential expansion. However, the figures remain part of the reported outlook for the next five years rather than a confirmed funding decision announced by Katayama.
The United States has urged Japan to raise defence expenditure to 3.5% of gross domestic product (GDP), arguing that this level should become a global standard for its allies.
The US pressure adds an important international dimension to Japan’s budget discussions. Any move towards the proposed spending level would require Japanese policymakers to consider both the country’s defence requirements and the financial arrangements needed to support a larger military budget.
For the government, determining the amount of defence spending is only one part of the process. Officials must also consider how additional expenditure could be funded, including whether changes to taxation or other revenue measures might be necessary. Katayama’s statement made clear that these questions have not yet produced a definitive outcome.
A possible corporate tax increase has attracted attention because it could provide an additional source of government revenue. Nevertheless, the finance minister’s remarks offered no confirmation that businesses would face higher taxes to cover the planned expansion. The government is still assessing the capabilities it needs before deciding on the appropriate spending level and how that expenditure should be financed.
The timing of the discussions is significant as Japan prepares its defence strategy for the coming five years. The reported possibility of annual spending exceeding 10 trillion yen suggests that the country could allocate substantially more resources to defence than it does under its current fiscal-year budget.
However, the final budget and its funding arrangements will depend on decisions that have yet to be announced. The government has not identified a specific financing method, and the corporate tax proposal remains a reported possibility rather than an established policy.
Katayama’s comments therefore leave two central questions unresolved: how much Japan will ultimately spend on defence and where the additional money will come from. The answers will shape the government’s approach to expanding its military capabilities while determining the financial burden associated with its security plans.
Based on currency conversion that exchange rate, the reported annual defence spending level of 10 trillion yen would be equivalent to approximately $63.08 billion. For now, Japan’s authorities are continuing to assess the scale of the defence expansion before committing to a funding strategy. With pressure from Washington to increase military expenditure and reports pointing towards a larger five-year defence budget, the government’s eventual decisions on spending and taxation will remain important developments to watch.
Finance
Alphabet Becomes Berkshire Hathaway’s Third-Largest Stock Investment
Berkshire Hathaway significantly increased its investment in Alphabet during the second quarter of 2026, making the Google parent company its third-largest stock holding. The move reflects a major shift in Berkshire’s investment portfolio as the company begins deploying more of the substantial cash reserves accumulated under former CEO Warren Buffett.
In a regulatory filing on Friday, August 14, Berkshire Hathaway reported that it held nearly 106 million shares of Alphabet as of June 30. The position was valued at approximately $37.8 billion. That compares with 57.8 million shares held three months earlier, representing an increase of about 83%.
The Alphabet investment included a $10 billion purchase announced in June. Alphabet had planned the investment as part of efforts to expand its artificial intelligence infrastructure, an area that has required significant capital spending as technology companies compete to build advanced AI systems and computing capacity.
Alphabet now ranks behind only Apple and American Express among Berkshire Hathaway’s stock investments. Apple remained the company’s largest holding at the end of June, valued at $66 billion. American Express was second at $51.3 billion. Coca-Cola ranked fourth, followed by Bank of America in fifth place.
The changes came as Berkshire made a broader shift in its investment activity during the second quarter. The company purchased $23.5 billion worth of stocks and sold $3.7 billion, ending a 14-quarter period in which it had been a net seller of equities.
The increased stock purchases also coincided with a reduction in Berkshire’s enormous cash holdings. Cash and cash equivalents declined to $364.7 billion on June 30 from $380.2 billion at the end of March. The decrease was partly influenced by $4.5 billion spent on share buybacks.
Greg Abel, who succeeded Buffett as Berkshire’s chief executive at the end of 2025, has started putting more of the company’s financial resources to work. Buffett continues to serve as Berkshire’s chairman and said last month that the decision to invest in Alphabet was his idea. Berkshire first began building its Alphabet position during the third quarter of 2025.
Buffett also said that he and Abel continue to consult with each other on Berkshire’s capital allocation decisions. Abel previously said that he was responsible for 94% of Berkshire’s stock holdings, while investment manager Ted Weschler managed the remaining 6%. The latest filing, however, did not identify which executive was responsible for individual purchases or sales.
Berkshire also made several smaller adjustments to its portfolio during the quarter. Its investment in Delta Air Lines increased by 44% to 57.3 million shares, worth nearly $5.4 billion at the end of June. The company also more than doubled its Macy’s position to approximately 7.3 million shares, valued at $173 million.
At the same time, Berkshire completely exited its investment in beverage company Constellation Brands. The position had been established about a year and a half earlier.
The conglomerate increased its holdings in homebuilder Lennar and disclosed a small $580,000 investment in another homebuilder, D.R. Horton. It reduced positions in Ally Financial, Bank of America, Capital One, kidney dialysis provider DaVita, grocery chain Kroger and steelmaker Nucor.
The disclosed stock holdings represented most of Berkshire’s $323.8 billion equity portfolio invested in U.S.-listed companies as of June 30. The portfolio changes provide an indication of how Berkshire is adjusting its investment strategy under Abel while Buffett remains involved as chairman.
Beyond its publicly traded investments, Berkshire Hathaway owns a wide range of operating businesses. These include BNSF railroad, Geico car insurance, energy and manufacturing operations, as well as consumer brands such as Brooks, Dairy Queen, Fruit of the Loom and See’s.
The stronger position in Alphabet marks one of Berkshire’s most significant recent investments and places the technology company among the conglomerate’s most important publicly traded assets.
Finance
Australian Shares Edge Lower as Westpac Drags Banks Ahead of RBA Rate Decision
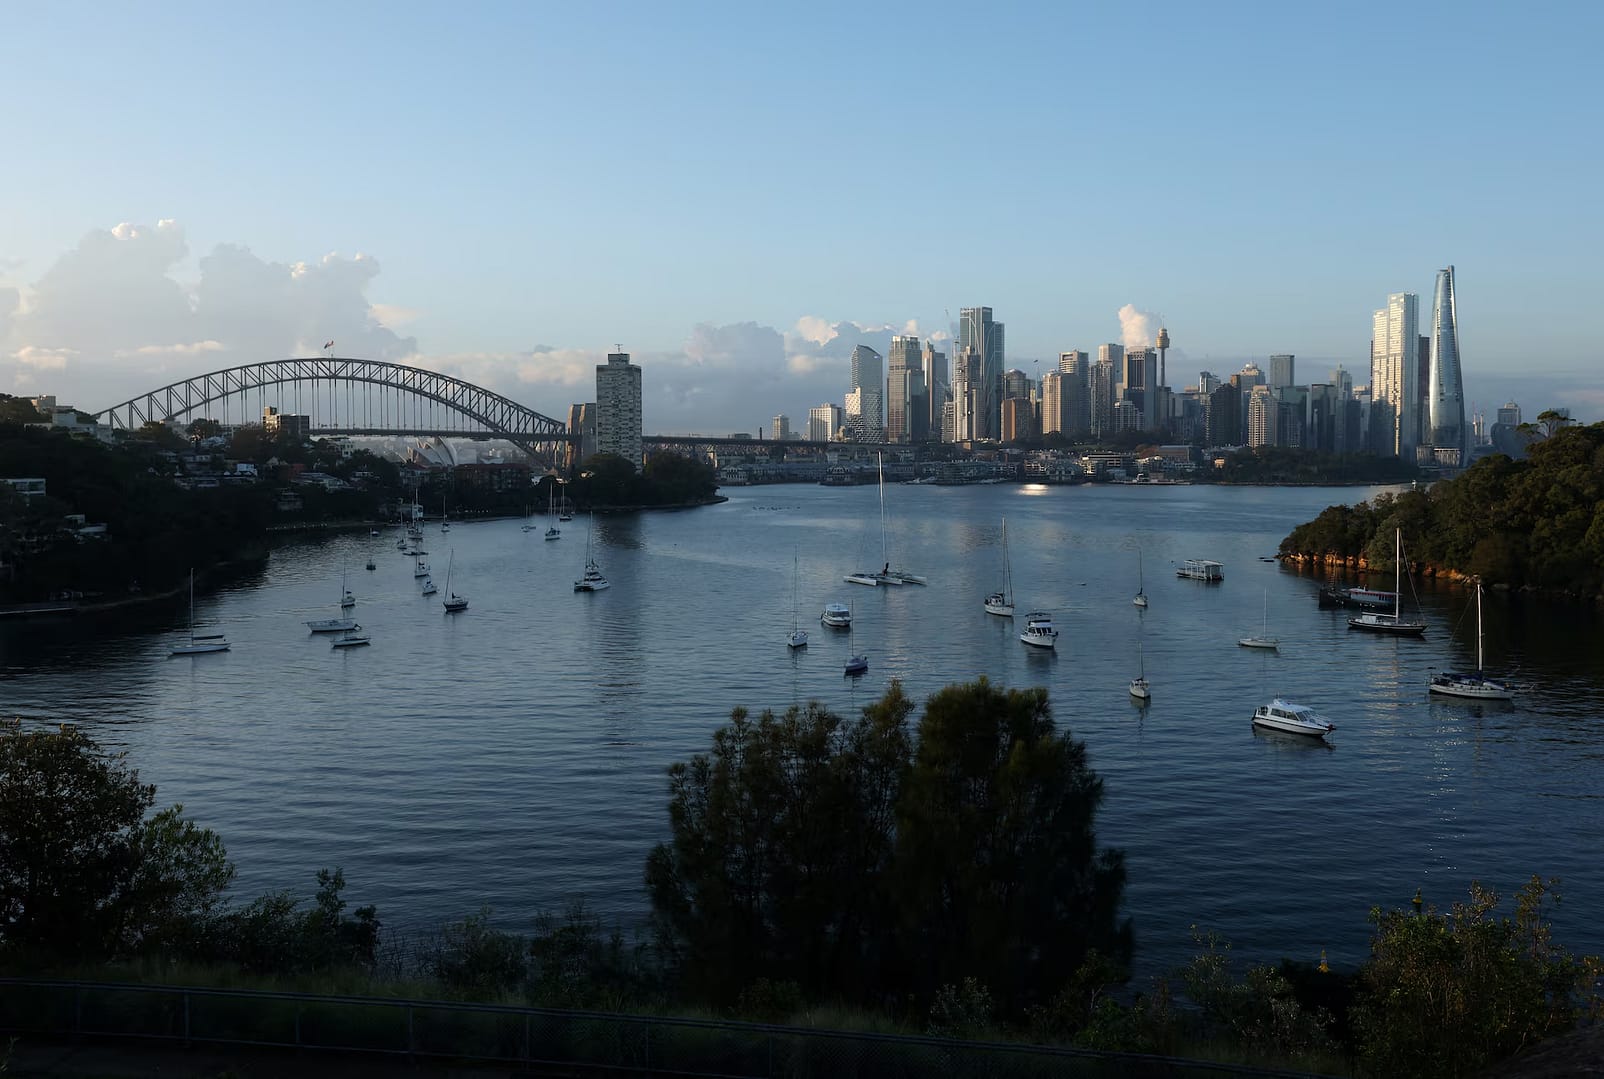
Australian stocks moved lower on Monday, August 10, as a sharp decline in Westpac shares pressured the banking sector, offsetting gains among mining companies. Investors were also positioning ahead of the Reserve Bank of Australia’s monetary policy decision, due on Tuesday, with markets largely expecting interest rates to remain unchanged.
The benchmark S&P/ASX 200 index fell 0.5% to 9,220.30 points by 0057 GMT. The index had advanced 3.2% during the previous week, but the latest session reflected renewed caution among investors as companies entered a closely watched fiscal 2027 earnings season.
Westpac was among the biggest drags on the market. Its shares dropped more than 5% during intraday trading, marking their steepest decline since March 30. The fall followed the lender’s quarterly update, which included weaker mortgage application figures and a more cautious outlook for housing credit growth.
Westpac said investor housing credit growth could halve next year and reported a 20% decline in mortgage applications. The bank recorded cash earnings of A$1.8 billion for the quarter ended June 30, compared with A$1.9 billion during the same period a year earlier.
The weakness spread across Australia’s major banks. The financials sub-index dropped 1.9%, recording its biggest intraday decline in three months. Commonwealth Bank of Australia, ANZ and National Australia Bank all fell, with their shares declining between 1.3% and 2.4%.
The banking sector’s performance came as investors turned their attention toward the Reserve Bank of Australia. The central bank was scheduled to announce its policy decision on Tuesday. Financial markets broadly anticipated that the RBA would leave interest rates unchanged, while investors were expected to closely examine its assessment of the economy and any signals about the future direction of monetary policy.
Mining stocks provided some support to the broader market. The mining sub-index climbed 1.4%, helped by stronger metal prices. Major mining companies BHP Group and Rio Tinto each gained more than 1%, while Fortescue rose 0.7%.
Gold-related shares performed even more strongly. The gold sub-index advanced more than 3%, reaching its highest level since mid-April as it tracked gains in bullion prices. Gold miners Evolution Mining and St Barbara rose 1.3% and 4.7%, respectively.
Elsewhere in the market, Treasury Wine Estates was a notable gainer. Its shares jumped nearly 8% after the company announced plans to reduce the size of its U.S. North Coast vintages from 2026 and said it would write down inventory, primarily bulk wine.
The Penfolds owner also provided an updated earnings outlook. Treasury Wine Estates forecast unaudited fiscal 2026 earnings before interest, tax, SGARA and material items, or EBITS, at A$492.3 million. That figure was above its previous guidance range of A$480 million to A$490 million.
The contrasting performances across sectors left the Australian benchmark under pressure despite strong gains in mining and gold-related stocks. Investors remained focused on corporate earnings developments as well as the upcoming RBA decision, which was expected to provide further insight into the central bank’s assessment of economic conditions.
Across the Tasman Sea, New Zealand stocks moved in the opposite direction. The benchmark S&P/NZX 50 index gained 0.5% to reach 13,892.88 points.
The Australian market’s decline highlighted the differing forces influencing equities ahead of the RBA announcement. Weakness in major lenders, particularly Westpac, weighed heavily on the benchmark, while stronger commodity prices supported mining and gold stocks. The combination left investors balancing concerns about housing and banking conditions against continued strength in parts of the resources sector.

NextDC Shares Plunge 41.7% as Power Delays Force Revenue Cuts and Halt Expansion Plans

Japan Has No Decision on How to Finance Higher Defence Spending

Yes Bank Reports 65% Profit Growth as Supreme Court AT1 Bond Ruling Raises Financial Uncertainty

Argentina Explores Debt Management Strategies: Potential Debt Swap and IMF Discussions on the Horizon

Apple Introduces “Tap to Pay” Feature for iPhone, Allowing Contactless Payments

Hedge Funds Capitalize on U.S. Regional Banking Stocks Plunge: Insights and Implications
-
 Banking3 years ago
Argentina Explores Debt Management Strategies: Potential Debt Swap and IMF Discussions on the Horizon
-
 Technology3 years ago
Apple Introduces “Tap to Pay” Feature for iPhone, Allowing Contactless Payments
-
 Banking2 years ago
Hedge Funds Capitalize on U.S. Regional Banking Stocks Plunge: Insights and Implications
-
 Technology3 years ago
Aviation Industry Urges Swift Action Against GPS Spoofing Amid Growing Threats
-

 Technology3 years ago
Bitcoin Weakens as Regulatory Concerns and Market Sentiment Impact Cryptocurrency Market
-

 Technology3 years ago
FTX denies talks of acquiring Robinhood
-

 Business2 years ago
Overcoming Financial Hurdles: TotalEnergies’ Quest for Renewable Energy in Africa
-
 Forex2 years ago
Navigating Risks in Bank-Fintech Partnerships: Insights from U.S. Bank Regulator