Banking
Strategic Divestment of Australian Retail Loan Portfolio by HSBC to Blackstone Group
A definitive agreement concerning the sale of a A$36 billion ($25.30 billion) Australian home and personal loan portfolio to global alternative asset manager Blackstone was announced on Friday by banking institution HSBC, representing the largest single residential mortgage portfolio transaction recorded in global financial history. The strategic divestment forms a central component of an extensive organizational overhaul initiated by HSBC Chief Executive Officer Georges Elhedery, by whom executive management tiers have been streamlined, operating costs reduced, and non-core international operations systematically divested since his appointment in September 2024.
Under the terms agreed upon by both financial institutions, the completion of the transaction is anticipated during the first half of 2027, subject to necessary regulatory approvals being granted by Australian governmental authorities. It was disclosed by Blackstone that the acquired residential loan assets will be distributed across its specialized investment vehicles, specifically within the Blackstone Credit and Insurance, Tactical Opportunities, and Real Estate Debt Strategies funds. Furthermore, the operational administration and servicing of the mortgage book will be assigned to Pepper Money, an established Australian non-bank lender. Following the public disclosure of the agreement, equity shares in Pepper Money experienced an intraday increase of up to 6 percent, despite broader annual trading losses of nearly 20 percent recorded across the year.
Within Australia’s broader A$2.5 trillion domestic mortgage ecosystem, which continues to be overwhelmingly dominated by the nation’s major domestic banking institutions, a relatively minor market share was maintained by HSBC due to the absence of an extensive physical retail branch network. Positive market sentiment was generated across global equity exchanges following the announcement, resulting in HSBC shares reaching all-time high valuations in both Hong Kong and London. An intraday rise of 2.4 percent to HK$168.5 ($21.49) was recorded on the Hong Kong Stock Exchange, outperforming the benchmark Hang Seng Index, while London-listed shares advanced by 0.9 percent to a record 1,601 pence ($21.54) during early morning trading sessions.
From a financial accounting perspective, a net loss of less than $100 million is expected to be recognized by HSBC as a consequence of the portfolio sale by the first half of 2027. Concurrently, restructuring expenditures totaling approximately $300 million will be incurred in connection with the wind-down of Australian retail operations, alongside foreign currency translation losses estimated at $300 million. However, it was confirmed by bank representatives that no adverse impact on the institution’s Common Equity Tier 1 capital adequacy ratio will occur as a result of the accounting adjustments.
The strategic retreat from consumer lending in Australia aligns with a broader structural realignment executed by HSBC over recent years, during which consumer banking operations were exited across multiple international jurisdictions, including France, Greece, and Canada. The transaction follows recent divestment agreements, including the sale of HSBC’s Singapore insurance division to Germany’s Allianz SE and the transfer of its Indonesian retail and wealth management operations to Oversea-Chinese Banking Corporation. Moving forward, corporate capital and operational resources will be concentrated exclusively on corporate and institutional banking services across Australia and New Zealand.
Concurrently, a sustained commitment to deploying capital within the Australian residential housing market was reaffirmed by Blackstone, even as macro-economic headwinds exert downward pressure on domestic mortgage demand. Investor activity across the country has been tempered by elevated borrowing costs and recent regulatory tax adjustments. Reports published by major Australian lenders reflect broader market contraction, with mortgage application volumes declining by 10 percent at Westpac following federal budget announcements, while a 15 percent drop in quarterly loan applications was reported by National Australia Bank.
By reallocating capital away from retail mortgage originations toward high-margin wholesale and institutional banking, HSBC’s structural transformation highlights a growing preference among multinational banking groups to eliminate low-yielding, non-core consumer portfolios. Simultaneously, the acquisition of high-volume loan assets by institutional private credit managers like Blackstone illustrates a continuing shift in global credit markets, where non-bank entities increasingly absorb residential mortgage risk from traditional commercial banking balance sheets.




Banking
HDFC Bank Puts Forward Two Names for Next CEO as Jagdishan’s Exit Approaches
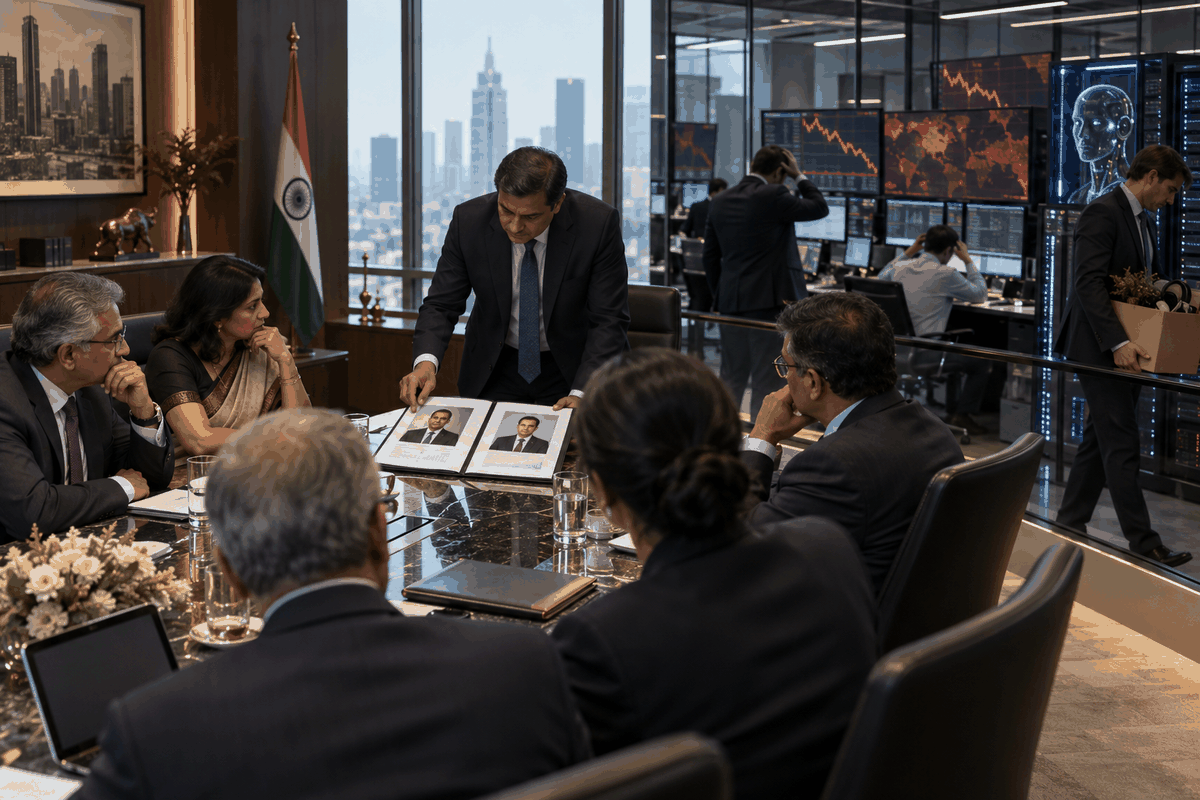
HDFC Bank has taken the next step in its leadership succession plan by forwarding the names of two candidates to the Reserve Bank of India (RBI) for the position of managing director and chief executive officer. The move comes ahead of the planned departure of Sashidhar Jagdishan, whose second term at the helm of the bank is scheduled to conclude in October.
The lender confirmed the submission on September 12 but did not identify either of the candidates. By sending the names to the central bank, HDFC Bank has officially entered the regulatory phase of its search for a new chief executive.
Jagdishan has been leading HDFC Bank since 2020 and is expected to step down when his second term ends in October. His impending exit makes the appointment of his successor an important decision for the bank as it prepares for a new phase of management.
The RBI has a statutory role in such appointments. Under India’s banking framework, private-sector lenders need the central bank’s approval before appointing a managing director or chief executive officer. As a result, the two individuals proposed by HDFC Bank will have to go through the regulator’s review before the bank can finalize its next CEO.
The lender has not disclosed which candidate it prefers or provided any details about the two people whose names were submitted. The absence of public information means the final choice remains unclear while the RBI considers the proposals.
Alongside the CEO succession process, HDFC Bank is strengthening its board. The bank has reappointed V. Srinivasa Rangan as a whole-time director. In banking, a whole-time director is a board member who holds a full-time executive role within the institution.
HDFC Bank has also appointed Jimmy Tata, who serves as its Chief Credit Officer, to the board as a whole-time director. The changes increase the representation of senior executives on the board at a time when the lender is preparing for a change in its top management.
Deputy Managing Director Kaizad Bharucha is already a whole-time director of the bank.
The lender has further decided to add another whole-time director position to its board. According to HDFC Bank, that fourth position will eventually be occupied by the new CEO after the successor has been selected and received the required approval.
The leadership transition comes after a period of significant change for HDFC Bank. In 2023, the lender completed its merger with Housing Development Finance Corporation, a major development that reshaped the structure and scale of the financial institution. The appointment of a new CEO will consequently be closely observed as the bank continues operating under the post-merger structure.
Jagdishan assumed the CEO role in 2020 after Aditya Puri, who had headed HDFC Bank for more than 20 years, stepped down. During Jagdishan’s tenure, the bank has navigated the merger with HDFC Ltd. and the organizational changes that followed the combination.
The incoming chief executive will take charge at a time when India’s banking sector is undergoing continuing changes involving regulation, digital technology and competition. The appointment will also shape HDFC Bank’s strategic direction as it enters its next period under new leadership.
For the moment, however, the identities of the two candidates remain undisclosed. The RBI’s assessment will be an essential part of the appointment process, and the final decision will determine who succeeds Jagdishan when his term comes to an end in October.
Banking
RBI Actions, Global Cues Set to Shape Rupee and Bond Markets This Week
The Indian rupee and government bond markets are expected to remain closely tied to the Reserve Bank of India’s policy actions this week, with the central bank’s foreign exchange intervention and efforts to manage surplus liquidity likely to be key domestic drivers. Global developments, particularly oil prices and expectations for U.S. interest rates, are also expected to influence market sentiment.
The rupee gained 0.9% last week, reaching its strongest level in two months before ending at 94.4850 per dollar. The rise came as the RBI continued selling dollars in the market and traders anticipated that the central bank could use its larger foreign exchange reserves to provide further support to the currency.
Anil Bhansali, head of treasury at Finrex Treasury Advisors, said the RBI has become the most important factor for the rupee. He noted that the central bank had shielded the currency from unfavorable external signals during the previous week, leaving investors focused on whether that support would continue.
The rupee enters the week against a more challenging global backdrop. Expectations of a Federal Reserve rate hike at its September meeting have increased following stronger-than-expected U.S. employment figures. U.S. nonfarm payrolls increased by 162,000 last month, substantially above the 56,000 rise economists surveyed by Reuters had forecast.
Markets will now turn their attention to U.S. inflation figures. The August consumer price report is scheduled for Friday evening, only a few days before the Federal Reserve’s policy meeting. The inflation data could have an important influence on expectations for the Fed’s next policy move, with market bets currently closely balanced.
Oil prices are another major factor for both currencies and bonds. Brent crude jumped 7.8% last week to reach a six-week high. Investors are monitoring developments in tensions between the United States and Iran, particularly any escalation that could affect global oil supplies.
Bond Market Faces Pressure
Indian government bonds are expected to trade with a negative bias this week after benchmark yields increased for a third consecutive week. The 10-year government bond yield finished Friday at 6.9625%, representing a 5-basis-point increase over the week. This followed a rise of approximately 15 basis points during the preceding two weeks.
Market participants expect the benchmark yield to remain within a range of 6.90% to 7.00%. Traders are likely to watch movements in crude oil prices as well as the RBI’s measures to regulate liquidity in the financial system.
Shorter-maturity government bonds have continued to receive support as liquidity in India’s banking system climbed above 10 trillion rupees ($105.84 billion) for the first time. The unusually large surplus has strengthened expectations that the RBI will need to adopt longer-lasting measures to absorb excess cash.
As part of those efforts, the RBI is scheduled to conduct a 30-day variable-rate reverse repo auction worth 7 trillion rupees on Monday. The operation includes an early redemption option, designed to encourage banks to place surplus funds with the central bank while allowing them flexibility to withdraw those funds earlier.
The combination of higher oil prices and rising U.S. Treasury yields has weakened sentiment toward Indian government bonds. However, some international investors continue to view the country’s debt market favorably.
Matthew Kok, fixed-income portfolio manager at Eastspring Investments, said Indian government bonds remain comparatively attractive on both fundamental and valuation considerations. He pointed to stronger growth prospects, an improved currency and greater stability in bond prices, along with the removal of withholding tax, as factors that have increased the attractiveness of Indian debt relative to local-currency bonds in other regional markets.
Several U.S. economic indicators are also scheduled for release during the week. Initial weekly jobless claims for the week ending September 5 are due on Thursday, September 10, along with August producer price and manufacturing-related data. August existing home sales are also scheduled for September 10.
The main focus will come on Friday, September 11, when the August consumer price and core inflation figures are due. A Reuters poll puts inflation at 3.4%. The preliminary September University of Michigan consumer sentiment reading is also expected that day.
Together, these domestic and international developments are likely to determine the direction of the rupee and Indian bond markets as investors assess RBI intervention, liquidity conditions, oil prices and the outlook for U.S. monetary policy.
Banking
Top Banks in Brazil Cut Risk as Household Debt Pressures Rise

Brazil’s largest banks are becoming increasingly cautious about lending as rising household debt raises concerns about the ability of consumers to manage additional borrowing. Despite a resilient labor market and economic growth that has exceeded expectations, major lenders are shifting away from riskier customers and unsecured loans.
The latest earnings reports from Banco do Brasil, Itau, Bradesco and Santander Brasil showed a broadly similar approach. Bank executives said they are placing greater emphasis on borrowers with higher incomes and loans supported by collateral, while reducing exposure to customers considered more vulnerable.
Katherine Hennings, an analyst at BRCG, said the shift reflects the need for banks to apply stricter standards when assessing borrowers. She noted that Brazil could be entering a slower stage of its credit cycle after several years in which increased household borrowing helped sustain economic activity.
Historically, periods of rapid credit expansion followed by rising household indebtedness have contributed to weaker consumer spending. Hennings pointed to Brazil’s experience between 2011 and 2015, when a sharp increase in household debt was followed by a significant slowdown in consumption.
The current situation presents a particular concern because household finances have weakened even while unemployment remains low and incomes have improved. Family debt obligations are close to record levels, standing at about 50% of disposable income.
Several factors have contributed to the increase. Regulatory changes, the expansion of fintech companies and the widespread use of digital payments have made borrowing more accessible to consumers who previously had limited access to financial services. Government measures designed to encourage consumption and credit have also contributed to higher household borrowing.
Some of that additional borrowing has come through expensive unsecured products, including credit cards and personal loans. These are precisely the types of lending that major banks are now becoming more reluctant to offer to lower-income customers.
Banco do Brasil expects the economy to grow by about 1% in 2027, below the median forecast of 1.5% from more than 100 economists surveyed weekly by Brazil’s central bank. The economists expect growth of around 2% this year.
Geovanne Tobias, Banco do Brasil’s vice president for finance, said the bank expects consumer delinquency to improve next year as it continues concentrating growth on payroll loans for public- and private-sector employees.
Itau CEO Milton Maluhy Filho offered a particularly cautious assessment, saying the amount of credit distributed in Brazil has surpassed what household incomes can comfortably absorb. He said the bank’s outlook had weakened at the margin and that Itau was responding by increasing its focus on secured loans while reducing unsecured consumer lending.
Bradesco has adopted a similar strategy. CEO Marcelo Noronha said the bank has become significantly more selective, particularly when dealing with lower-income customers. He added that a larger share of the bank’s lending portfolio is now supported by collateral.
Santander Brasil has also reduced its exposure to borrowers it considers higher risk. The bank is paying particular attention to customers earning less than 4,000 reais ($771.40) per month, equivalent to roughly 2.5 times Brazil’s minimum wage.
Carlos Muniz, Santander Brasil’s chief financial officer, said the bank would not currently compete for customers below that income threshold. For borrowers earning more than 4,000 reais, he said Santander would seek lending opportunities backed by some form of collateral. The strategy affects a substantial portion of Brazilian workers, with about 70% of employed people earning no more than twice the minimum wage.
Banco do Brasil CEO Tarciana Medeiros said the bank aims to increase its number of “high-value clients” by 25% by 2030, making the expansion of that customer base a central strategic objective.
Meanwhile, Nubank, Brazil’s largest digital lender and a company heavily exposed to credit cards and other unsecured loans, reported a rise in loans more than 90 days overdue. The figure reached 6.9% in the second quarter, compared with 6.5% in both the previous quarter and the same period a year earlier.
Nubank nevertheless reported stronger-than-expected profit growth, supported by increased revenue and an improved risk-adjusted net interest margin. Its management maintained that there was no broad deterioration among consumers, although it acknowledged a more cautious economic environment.
The banks’ changing lending strategies indicate that Brazil’s financial sector is preparing for greater pressure on household borrowers as economic growth is expected to slow.
HDFC Bank Puts Forward Two Names for Next CEO as Jagdishan’s Exit Approaches
EU Regulator Warns Markets Could Face Sudden Correction Amid Rising Risks
AI Investment Boom Raises Financial Stability Concerns, BIS Chief Warns

Argentina Explores Debt Management Strategies: Potential Debt Swap and IMF Discussions on the Horizon

Apple Introduces “Tap to Pay” Feature for iPhone, Allowing Contactless Payments

Hedge Funds Capitalize on U.S. Regional Banking Stocks Plunge: Insights and Implications
-
 Banking3 years ago
Argentina Explores Debt Management Strategies: Potential Debt Swap and IMF Discussions on the Horizon
-
 Technology3 years ago
Apple Introduces “Tap to Pay” Feature for iPhone, Allowing Contactless Payments
-
 Banking2 years ago
Hedge Funds Capitalize on U.S. Regional Banking Stocks Plunge: Insights and Implications
-
 Technology3 years ago
Aviation Industry Urges Swift Action Against GPS Spoofing Amid Growing Threats
-

 Technology3 years ago
Bitcoin Weakens as Regulatory Concerns and Market Sentiment Impact Cryptocurrency Market
-

 Technology3 years ago
FTX denies talks of acquiring Robinhood
-

 Business2 years ago
Overcoming Financial Hurdles: TotalEnergies’ Quest for Renewable Energy in Africa
-
 Forex2 years ago
Navigating Risks in Bank-Fintech Partnerships: Insights from U.S. Bank Regulator